From the newsletter (October 9; sign-up or follow if you want it sooner): Vodafone’s investor day revealed the scale and shape of its enterprise business, from £1.85 billion in annual service revenue to growth bets on network slicing, FWA, SD-WAN, cloud and security.
There was a lot in Vodafone’s investor day presentation yesterday (October 8), mostly about the minutiae of its jet-heeled integration with the old Three network in the UK. But alongside the talk about its site consolidation, spectrum deployment, and IT migration schedules, and its market gambit that it will create a more valuable operator entity from the depleted sum of its merged parts, it also provided a rare glimpse into the state of its bellwether business unit: Vodafone Business, which has its most advanced tech and most demanding customers. It even acknowledged in the intro – something like – that the division tends to be overlooked in such proceedings.
But the numbers in its slide deck are worth memorializing: Vodafone Business made £1.85 billion in service revenue 2025/26, about 27% of VodafoneThree’s total in the period. (As a point of note, the Three brand remains absent in its enterprise dealings, and one million Three business connections will be migrated-over, and cross-sold and up-sold.) It has 6.5 million mobile connections and 15.3 million IoT connections (which are surely owned, in some-way I forget, by Vodafone IoT); it is adding the latter at a rate of 11,500 per day, it says. No SaaS numbers, except that its SaaS service revenue grew 41% at last count. So big numbers, really.
More interesting, and more relevant to its strategy, is its enterprise segmentation, and the scores on the doors: small/home office (SoHo) firms, with a single site and fewer than 10 staff, make up 27% of its divisional revenue (and 20% of all UK business revenues); small/medium-sized enterprises (SMEs), with fewer than 250 staff and more than one site, make up 23% (and 30%, respectively); bigger private enterprises with even more employees and offices, make up 31% (and 27%); and public sector organizations, of all sizes, make up 19% (23%). “We’re strong in SoHo and private; we’ve got headroom to grow In SME and public,” said Vodafone Business director Nick Gliddon.
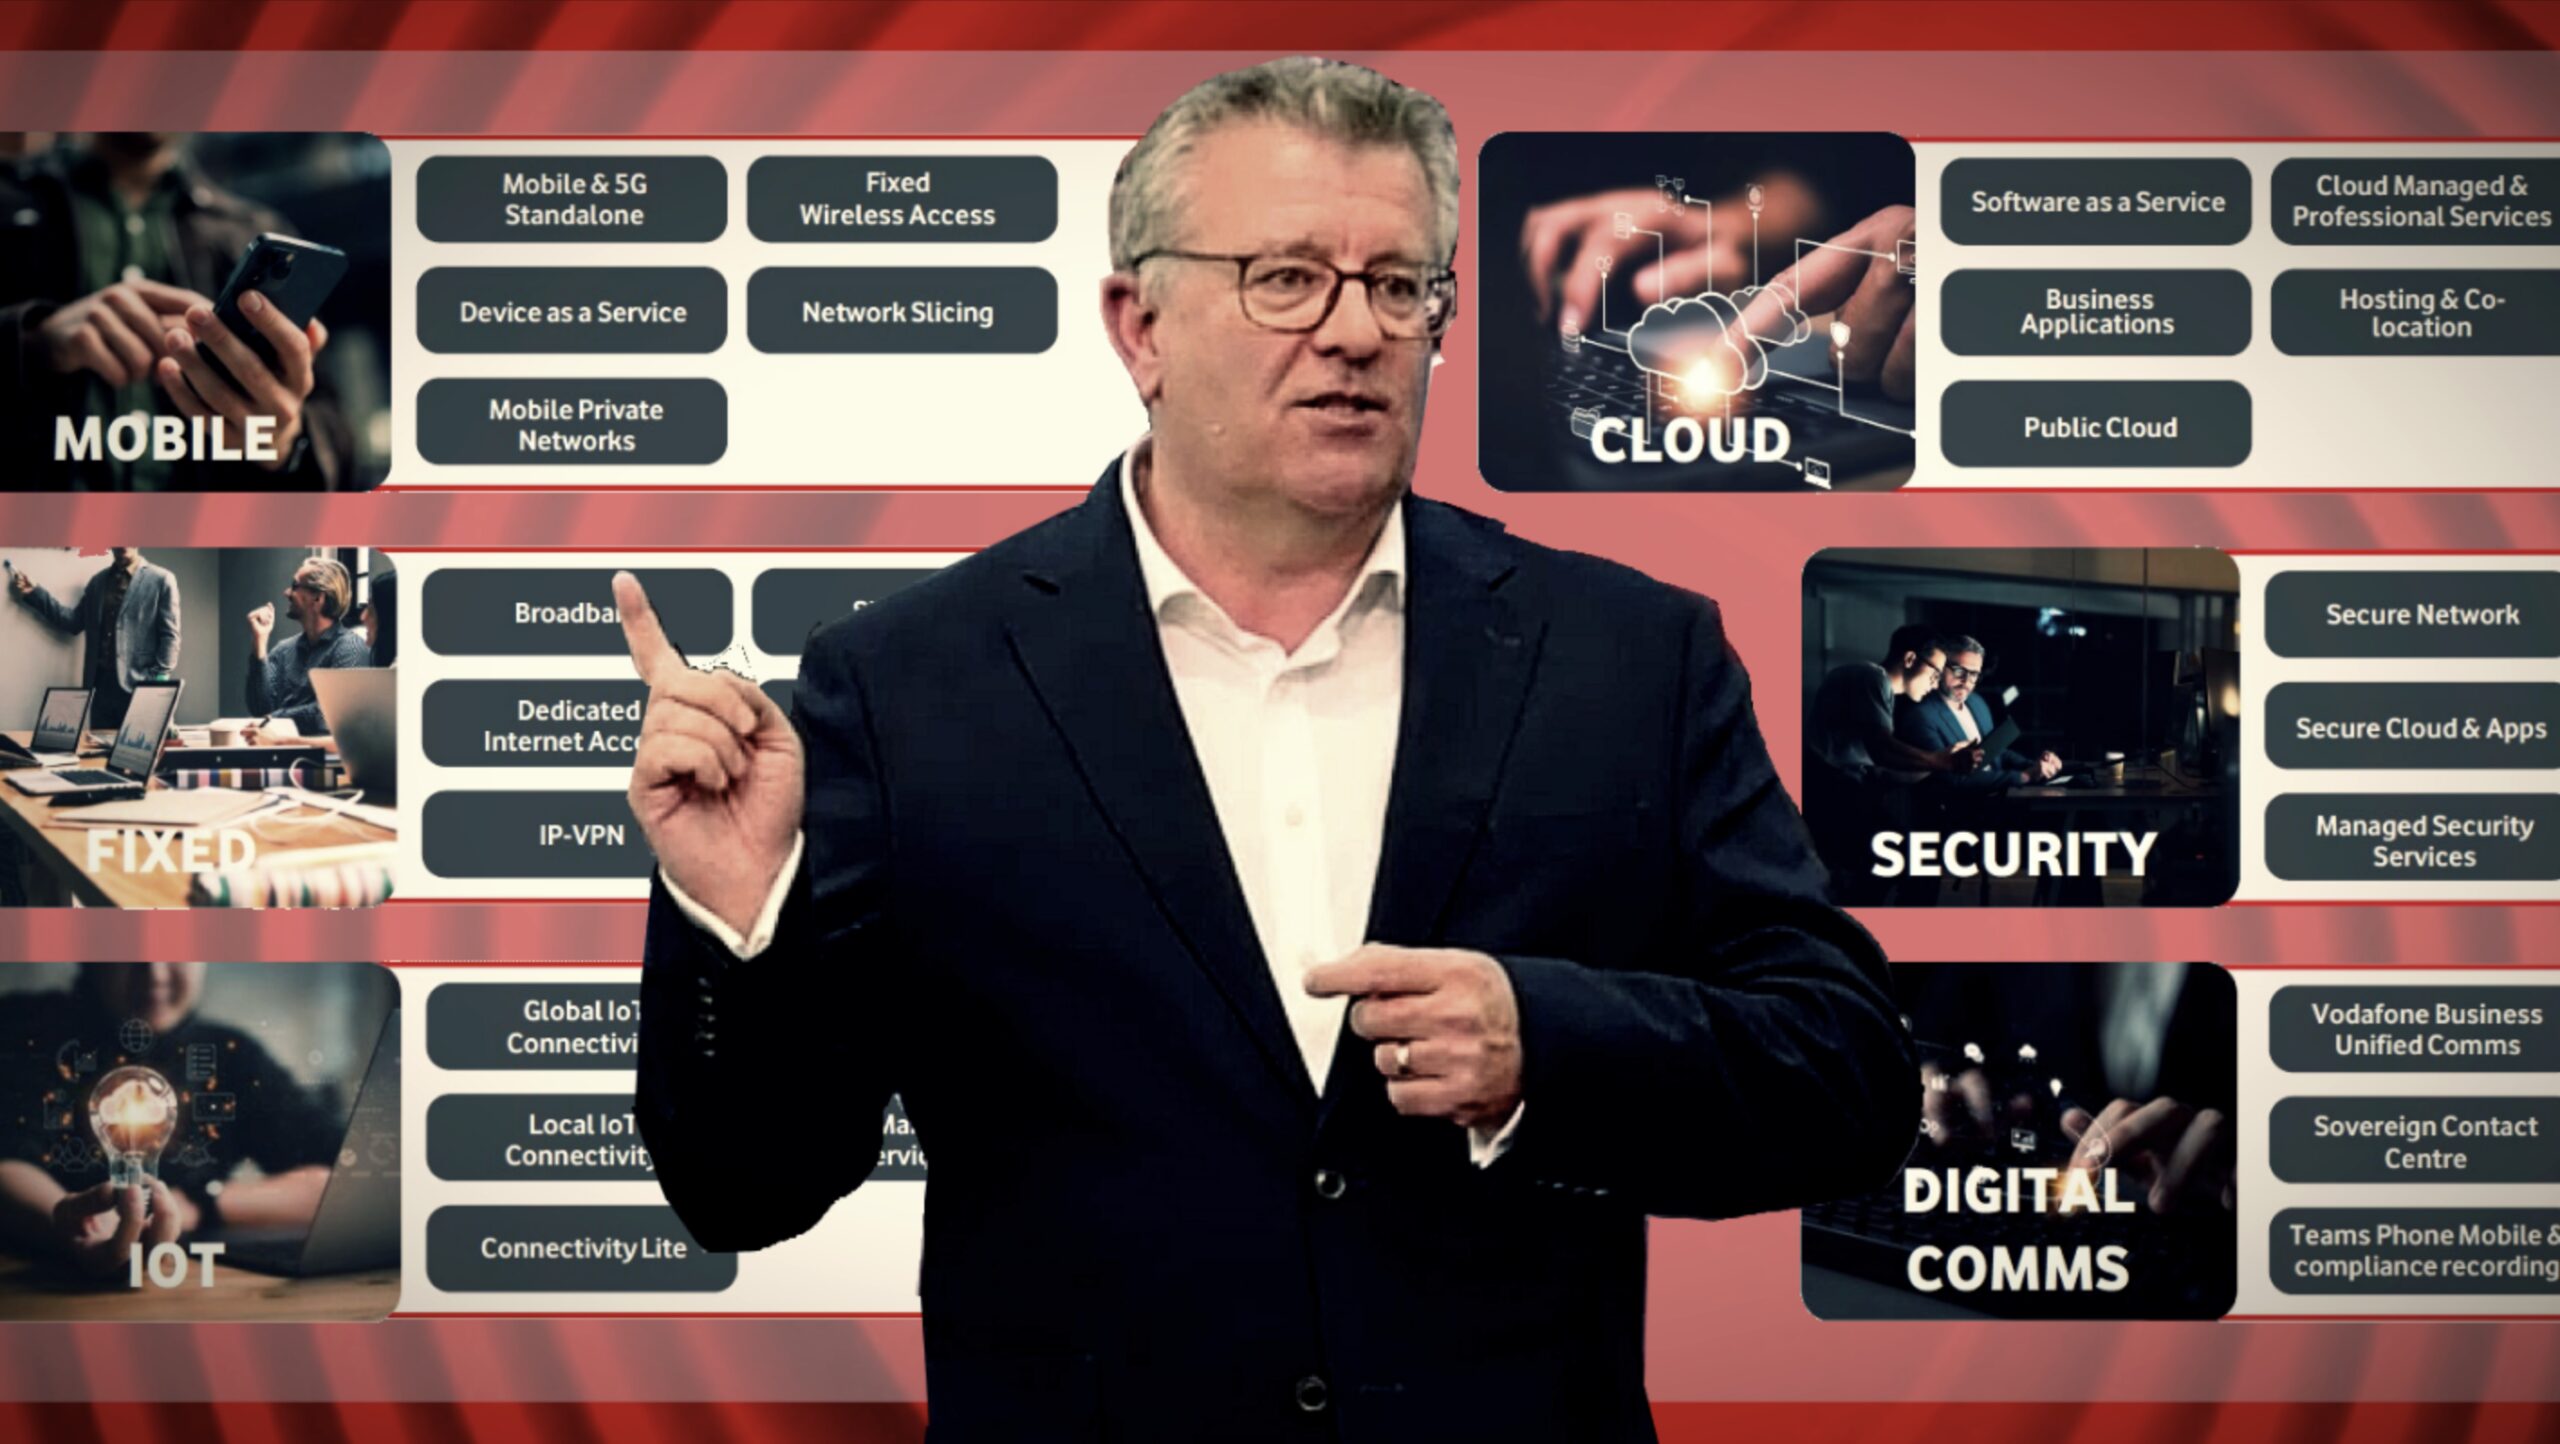
Some useful portfolio and market numbers, before we make a point. ‘Mobile’ (5G etc), as presented, comprises 50% of its service revenue; this includes private networks, FWA, and slicing. Note: this was the only mention of private networks in three and a half hours of presentations. FWA fared better; slicing was everywhere. The rest of its money comes from ‘fixed’ services (26%, broadband, private internet, VPNs, SW-WAN, Ethernet), IoT (just 6%; I mean, we knew it was tight, but…), cloud (8%; business apps, public cloud, pro services, hosting, co-location), security (7%), and ‘digital comms’ (7%), which covers unified comms and other bits.
For UK operators in the enterprise market, Vodafone is tops for mobile, it reckons (based on Analysys Mason et al): a 41% share, leading from BT/EE (30%), VMO2 (25%), and others (5%). For fixed, it trails BT/EE and a hode-podge of ‘others’ by a distance (14%, from 47% and 33%; VMO2 is even further back). Where are the opportunities? Gliddon had another slide, showing CAGR forecasts (to 2030) for every discipline: mobile will grow by 0.9%, fixed by 1.5%; slicing will jump (from nothing, let’s be honest) by 31%; FWA and SD-WAN will grow 14% and 13%, respectively. Beyond, there’s double-digit growth in cloud (14%) and security (10%). IoT rates are middling, at 6%.
So, what is our point here, apart from sharing rare and revealing figures? Well, you’ll have to catch us next week for that. We are out of room, and out of time. But think on the numbers: the clues are in those enterprise segments, plus its target industries (which reflect Nokia’s new private-networks rationale), and all its talk about slicing; plus, as well, in networks chief Andrea Donà’s comments about AI infrastructure and AI-RAN – which sound entirely pragmatic, if not a little – dare we say it – British, or just un-American. AI really didn’t feature much, but for some forced Q&A responses. In the meantime, the weekend beckons – and it’s a long one for Columbus Day (?) in the US, so we’ll catch you Tuesday.